

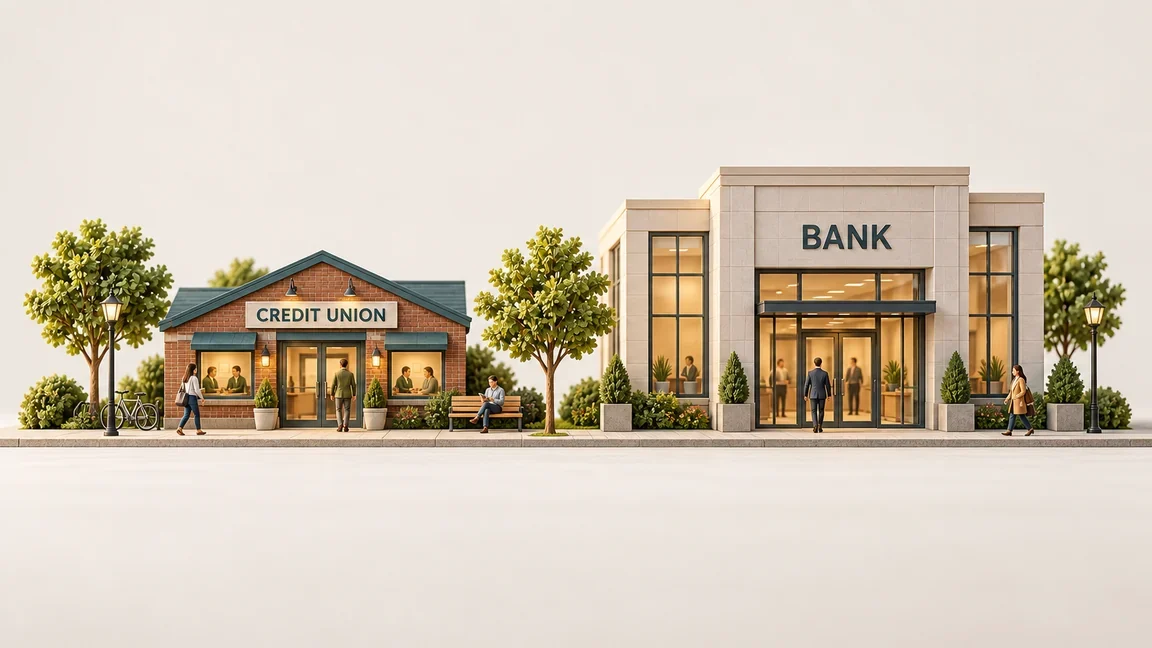
Credit union vs. big bank: when switching makes sense
Compare credit unions and big banks on fees, loan rates, insurance and access, plus four credit unions to consider and what to check before switching.
If your bank charges a monthly checking fee or gives you a high car-loan quote, a credit union is worth comparing. You may find lower costs without giving up the services you use.
Here is how credit unions compare on fees, rates, insurance and convenience, plus four to consider and what you need to join.
Key takeaways
- 1
Credit unions may offer lower checking fees and loan rates, but savings rates are not always better.
- 2
Compare branch access, cash deposits, transfer limits and account requirements before switching.
- 3
Federal NCUA insurance covers eligible deposits within limits that depend on account ownership.
- 4
Alliant, PenFed, Navy Federal and Connexus suit different banking needs.
- 5
Test a new account before moving all your income and bills.
How is a credit union different from a bank?
A credit union is a not-for-profit financial cooperative owned by its members. Members elect its board, and earnings can support lower fees, better deposit rates and lower loan rates. You generally qualify through a connection such as your community, employer, family or an eligible association. NCUA's consumer guide explains how membership works.
Credit unions still charge fees and set lending standards. Their services also vary: one may operate mainly online, while another has branches near your home or workplace.
Where a credit union can offer a better deal
Checking with no monthly maintenance fee
A fee waiver tied to direct deposit or a minimum balance can be inconvenient if your income varies or you keep most of your savings elsewhere.
Both PenFed Free Checking and Alliant checking have no monthly maintenance fee or ongoing minimum balance requirement. PenFed requires $25 to open; certain transaction fees still apply.
Check your statements to see what switching would save. Avoiding a $12 monthly fee saves $144 a year. If you already pay no monthly fee, compare other costs, including overdrafts, wires, paper statements and ATM withdrawals.
A lower rate on your next loan
Get a credit union quote when shopping for a loan. In the NCUA's December 26, 2025 comparison, the national average rate for a 60-month new-car loan was 5.44% at credit unions and 7.41% at banks.
These historical averages include banks of different sizes. Your current quote will depend on factors such as your credit profile, vehicle, loan term and available discounts.
Compare APRs, fees and total repayment costs for the same amount and term. Extending a loan can lower the monthly payment while increasing its total cost. Before requesting a quote, ask whether the rate check requires a hard credit inquiry.
Interest on your checking balance
Some credit unions pay interest on checking balances when you meet monthly activity requirements. These accounts can work well if you already make the required deposits and debit purchases.
Check the balance cap and what you earn if you miss a requirement. Calculate interest on your full balance, including money above the cap. If you would shift spending from a rewards credit card to a debit card, subtract the rewards you would lose.
Credit unions do not lead on every deposit product. In the same December 2025 NCUA comparison, ordinary savings rates averaged 0.19% at credit unions and 0.32% at banks. Compare individual high-yield accounts before moving your savings.
Our guide to how small banks and credit unions can out-pay megabanks explains how some of these offers work.
Convenient local service
A nearby credit union may be useful if you prefer in-person help. Check its hours and ask how it handles services you might need, such as a replacement debit card or a cashier's check.
Some credit unions participate in shared branching or shared ATM networks. These provide different services: access to another institution's ATM does not necessarily mean you can use its tellers. Confirm the services, deposit options, limits and fees at the locations you would use.
If you bank mostly online, try the app and contact support with a question before moving your main account.
Is your money insured at a credit union?
At a federally insured credit union, standard coverage is $250,000 per share owner, per insured credit union, for each account ownership category. The National Credit Union Share Insurance Fund is administered by the NCUA and backed by the full faith and credit of the United States. Read the NCUA's share insurance explanation.
Opening several accounts in the same ownership category at one credit union does not give each account a separate $250,000 limit. Some state-chartered credit unions use private insurance, so verify federal coverage with the NCUA credit union locator. Share insurance protects covered deposits if the institution fails; it does not cover investment losses.
Four credit unions worth comparing
Account and membership information below was reviewed September 9, 2026. Check current rates, fees and eligibility before applying.
| Credit union | Consider it for | Main requirement to check |
|---|---|---|
| Alliant | Online banking and ATM fee rebates | Membership and checking dividend requirements |
| PenFed | Checking without a monthly service fee | Opening deposit and convenient branch or ATM access |
| Navy Federal | Banking for eligible military and Department of Defense households | Membership eligibility and checking account features |
| Connexus | Rewards checking if you regularly use a debit card | Monthly deposits, debit purchases and the balance cap |
Alliant: online banking and ATM fee rebates
Alliant is worth considering if you are comfortable banking online. Its High-Rate Checking account advertises up to $20 in monthly ATM fee rebates. Earning checking dividends requires electronic statements and a qualifying monthly electronic deposit; review the official checking disclosures.
Several membership routes are available. If you do not qualify through an employer or family connection, Alliant offers membership through the Alliant Credit Union Foundation and pays its one-time $5 fee on your behalf. See Alliant's membership rules.
Before applying, check cash-deposit options, transfer limits and the requirements of your chosen checking tier.
BankRewards also lists an Alliant savings offer. This separate promotion has its own opening and funding terms.
PenFed: checking without a monthly service fee
PenFed Free Checking has no monthly service fee or monthly minimum balance requirement. You need $25 to open it. Certain transaction fees still apply; review the account details and fee links.
Military service is not required. PenFed says everyone is eligible to apply, though membership and account approval are still required.
Check whether its branches, ATMs and cash-deposit options are convenient for you. Compare savings products separately if you also plan to move money out of another savings account.
Navy Federal: eligible military and Department of Defense households
Navy Federal's membership includes specified servicemembers, veterans and Department of Defense personnel, plus qualifying family and household members. Confirm your eligibility on its membership page.
Its Free EveryDay Checking has no monthly service fee and no minimum opening deposit.
Check the features of the specific account you choose. An ATM rebate advertised for another Navy Federal checking product may not apply to Free EveryDay Checking. If you are joining to borrow, compare an actual loan quote with your other offers.
Connexus: rewards checking for regular debit-card users
Connexus Xtraordinary Checking advertised 4.50% APY on balances up to $25,000 when reviewed September 9, 2026. Qualifying balances above $25,000 earn 0.25% APY.
To earn dividends, each calendar month you must:
- Receive eStatements.
- Receive at least $500 in qualifying direct or external ACH deposits.
- Make at least 15 debit purchases or spend at least $500 in net debit purchases.
Purchases must post by month-end, and ATM transactions do not count. If you miss a monthly requirement, you earn no dividends that month. Rates can change; read the current account terms.
If you do not qualify another way, you can join the Connexus Association through a one-time $5 donation. A separate $5 savings balance establishes and maintains credit union membership.
Count any credit-card rewards you would give up to meet the spending requirements. You can also review the Connexus account on BankRewards.
When a big bank may be the better choice
An account that costs nothing and reliably handles your banking may be worth keeping. Convenient branches, easy cash deposits or services you use while traveling can matter more than a small increase in interest.
You can also use both institutions. A credit union might provide your car loan or savings account while your bank handles daily checking. Check whether keeping both adds fees or account requirements.
What to check before switching
- Membership and insurance. Confirm that you qualify and that your deposits will have the coverage you need. Distinguish a membership fee or donation from a savings balance you must maintain.
- Everyday access. Check branches, cash deposits, ATM fees, bill pay and wire services. Review transfer limits, new-account holds and mobile-deposit availability.
- Annual value. Estimate interest and rewards on your actual balance and spending, then subtract fees and any rewards you would lose elsewhere.
- Bonus terms. Check the required application link, eligibility, qualifying deposits, deadlines and how long you must keep the account open. A deposit that qualifies for checking interest may not meet a bonus's direct-deposit requirement.
- The move itself. Open the account with a manageable amount, activate the debit card and test a transfer. Keep enough in your old account for outstanding checks and scheduled payments until the new deposits and bill payments have worked.
Use our bank bonus ROI calculator to compare a one-time incentive with the balance and time it requires, or browse current checking and savings offers.
Related articles
How Small Banks and Credit Unions Out-Pay the Megabanks
The biggest banks pay the lowest rates by design. Here is the economics of why small banks and credit unions out-pay them, and how to find the good ones.
Checking Account Bonus or High-Yield Savings? Where Your Cash Earns More in 2026
With the Fed on hold and top savings rates around 4 percent, a single checking account bonus can out-earn a full year of interest on a modest balance. Here is the math and how to decide.
Does Opening Bank Accounts Hurt Your Credit? ChexSystems and Checking Bonuses
Opening checking accounts for bonuses usually affects your banking report more than your credit score. Learn how ChexSystems works, when hard pulls matter, and how to reduce denial risk.
Bank Bonus ROI Calculator
Calculate the true annualized return (APY) of a bank sign-up bonus and compare it against standard savings accounts.